Vendors selling claims adjudication automation tend to promise the same clean future: a claim arrives, software reads it, applies the plan rules, and pays or denies it with no person touching the file. The reality underneath that pitch is narrower than the demo. The DataSpring Index, the healthcare administrative benchmark long published as the CAQH Index, still finds roughly $21 billion in annual savings sitting in transactions handled by hand, and the automation that does exist is spread unevenly across the steps of a claim rather than being either absent or complete. The distance between the pitch and that picture is where a mid-market operation either spends well or burns a budget.
The word “adjudication” is doing two jobs at once
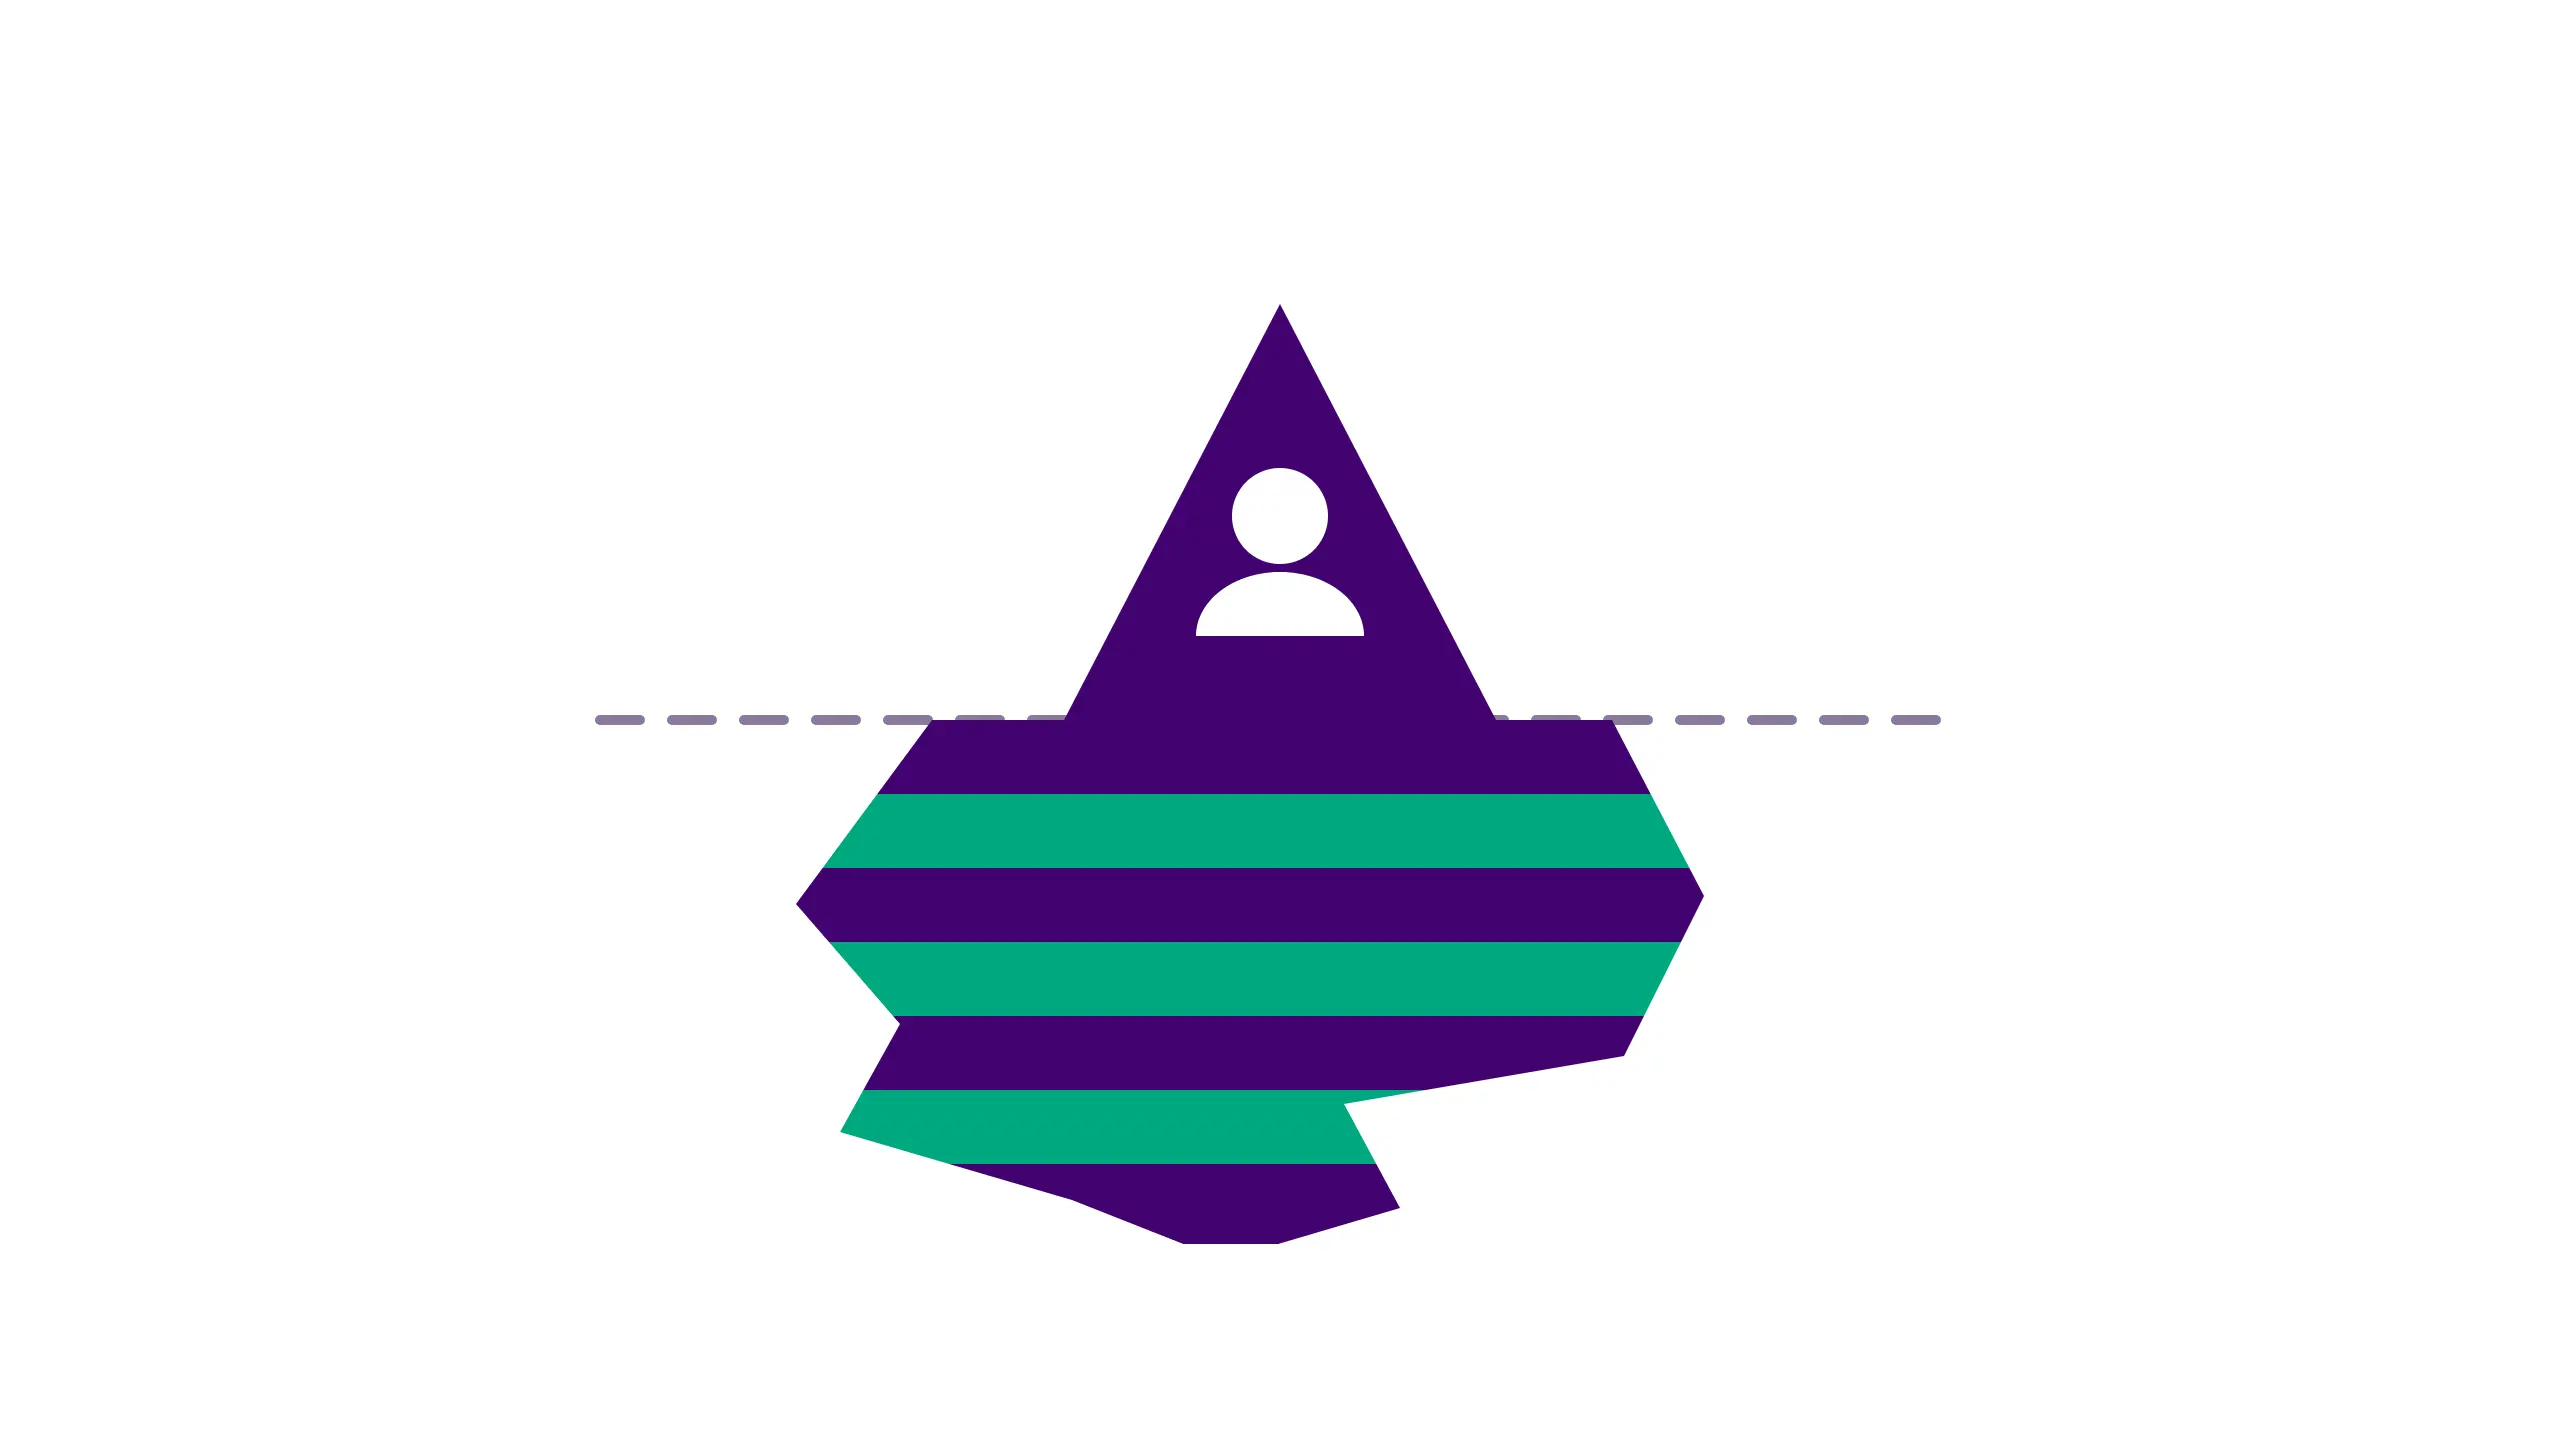
When a vendor says it automates adjudication, it usually means straight-through processing, where the system itself makes the decision on the claim from start to finish. When a claims director says the same word, they usually mean the whole journey a file takes from the inbox to a paid or denied outcome, most of which is preparation rather than decision. Those two meanings carry very different price tags and very different risks, and blurring them is how an operation ends up buying a decision engine when what it needed was to clear the work piling up in front of the decision.
A claim in a mid-market insurer or third-party administrator is a regulated case file, not a single transaction. Someone logs the first notice of loss, keys it into the administration system, pulls supporting documents from separate portals, checks the file against coverage or plan rules, and routes anything outside the clean path to a senior examiner. At Digital Forms we call the people holding that sequence together the Human API problem: skilled staff who spend their day as the connective tissue between a claims platform, a policy database, a clearing system, and a stack of portals nobody integrated. The adjudication decision sits at the end of that chain, and it is the smallest part of the labour behind a resolved claim.
Why the honest version of this question matters now
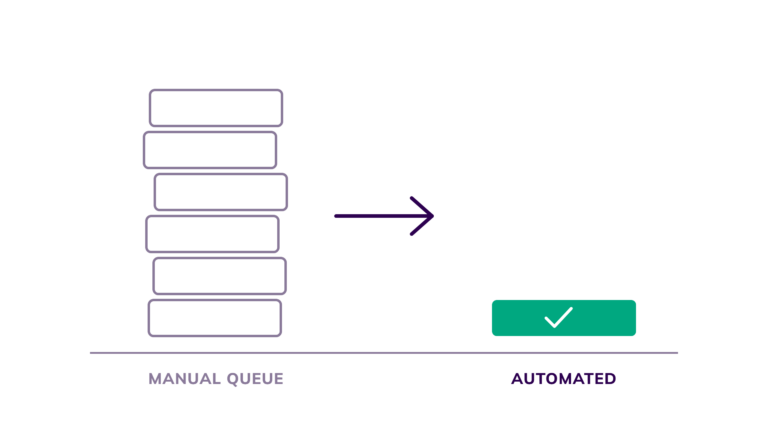
Two pressures have made the distinction expensive to ignore. The first is cost, and it has a recognisable shape on the financials. Claims headcount scales almost in a straight line with volume when the work between intake and decision is manual, so every growth year adds examiners whose time goes mostly to assembling files rather than judging them. Revenue rises, the headcount rises with it, and the cost of handling a claim never falls the way it should. This is the Manual Wall in a claims operation, the growth ceiling a business hits when it keeps absorbing volume with headcount because the systems underneath were never built to carry it, and the expensive part is the preparation no automation was ever pointed at.
The second pressure is law, and it has moved quickly. California’s Physicians Make Decisions Act, SB 1120, has required since January 2025 that a denial, delay, or modification of care based on medical necessity be made by a licensed human rather than an algorithm alone. New Jersey’s 2026 bill would extend the same principle to homeowner, automobile, and flood claims while still allowing automated approvals and triage, and Florida and Texas have advanced comparable measures. Read together, those laws draw a line the vendor pitch tends to smudge. Automating the approval of a clean claim is permitted and common, while automating the denial, the adverse decision a policyholder can appeal, is exactly the part regulators are now moving to keep in human hands. An operation that buys “full adjudication automation” without noticing which side of that line its claims fall on is buying a compliance problem alongside the software.
What is claims adjudication automation, really?
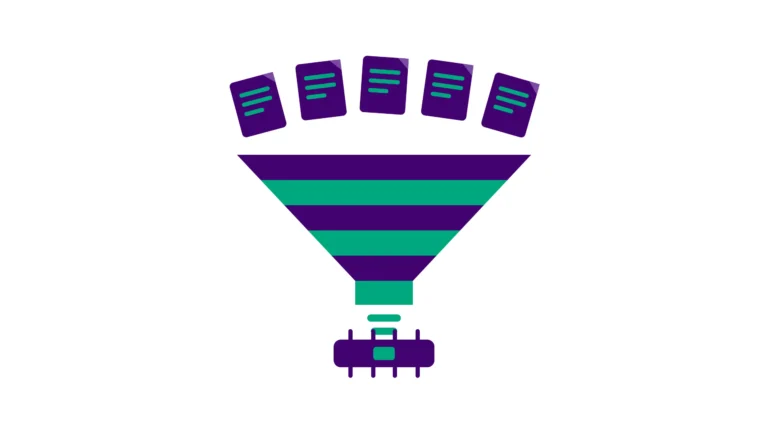
Strip the marketing back and there are two separate capabilities wearing one name. Straight-through processing is the decision engine, which ingests a claim, runs it against the rules, and resolves it with no human review. Workflow and document automation is the preparation layer, which turns inbound documents into structured data, moves that data between systems, retrieves the reports an examiner needs, and drafts the standard correspondence, so the person who does make the decision opens a file that is ready to judge. Both are real, both get sold under the same label, and they solve different problems at very different levels of risk.
For most mid-market operations the preparation layer is where the money sits, because that is where the hours actually go. A claims operation rarely struggles because its examiners decide too slowly. It struggles because those examiners spend most of the day on the clerical work around the decision, re-keying the same intake details into separate systems and reconciling documents by hand. Automating that layer returns capacity in the current quarter and carries almost none of the regulatory weight that automating the decision does, which is why it is the sane place to start and the place the vendor demo rarely begins.
Where does straight-through processing actually work?
Full auto-adjudication earns its place in a specific zone, and the boundaries are worth stating precisely. It works where claims are high in volume, low in individual value, governed by clear and stable rules, and arriving as clean structured data. A pharmacy claim checked against a formulary, a small auto-glass claim, a routine eligibility-driven payment: these resolve well without a person, because the rule is unambiguous and the input is tidy. The same benchmark shows how far this has already run in the clean lanes, with electronic adoption for claim status and claim payment sitting near four fifths of transactions and prior authorisation, a messier step, lagging well behind.
The zone ends where ambiguity begins, and mid-market books are full of ambiguity. A workers’ compensation file with a contested injury, a property claim with a manuscript endorsement, a medical case where the plan language does not cleanly fit the facts: each needs a judgment a rules engine cannot make safely. Pushing those files through straight-through processing does not remove the risk, it relocates the risk into a system that will apply a confident answer to a question that deserved a careful one. That is the failure mode behind the automated-denial lawsuits now working through the courts, and it is why the clean-lane success stories do not generalise to a whole mid-market book.
| Straight-through processing fits | Straight-through processing breaks |
|---|---|
| High volume, low individual value | High value, multiple parties, real exposure |
| Clear, stable rules | Ambiguous or contested rules |
| Clean, structured inputs | Unstructured documents and exceptions |
| Pharmacy, auto-glass, eligibility payments | Workers’ comp, manuscript endorsements, medical-necessity calls |
Is it legal to auto-adjudicate a claim with no human in the loop?
The honest answer is that it depends entirely on which way the decision goes, and the law has grown clearer about this over the last two years. Paying or approving a clean claim automatically is legal and routine. Denying one is where the constraints bite. The stakes there are not small, because an analysis by KFF published in 2025 found that HealthCare.gov insurers denied close to one in five in-network claims and that fewer than one percent of those denials were ever appealed. California’s SB 1120 has required since January 2025 that a licensed professional make a medical-necessity denial, and the comparable 2026 measures advancing in other states are pushing the same human-accountability requirement beyond healthcare into property, auto, and flood lines. Beneath that wave sits decades of unfair-claims-practices law requiring a reasonable investigation and a real explanation for a denial, which a black-box decision cannot readily supply.
None of this makes automation illegal, and it is worth saying plainly that approvals, triage, fraud scoring, and the whole preparation layer remain open territory. What the law increasingly forecloses is the single move the vendor pitch is proudest of, a denial issued end to end by software with no accountable human behind it. For a mid-market operation that turns “keep the examiner on the decision” from a preference into a design requirement, because the alternative now carries statutory exposure in a growing list of states. This is an informed reading of where the rules are heading rather than legal advice, and the enacted laws differ from the bills still working through their legislatures.
What should a mid-market claims operation automate first?
The first move is a measurement rather than a software decision. Before committing to any build, an operation needs to know where its handling cost and its cycle-time delay actually concentrate, which steps consume the most examiner time and which points put a regulatory clock at risk when volume rises. Surfacing that is what we built our Profit Leak Diagnostic to do at Digital Forms, because operators routinely assume the bottleneck is the adjudication queue itself and then find that the real drain is attachment handling or intake two steps upstream, starving every queue behind it.
From there the discipline is to sequence by recoverable value and build narrow, so the first result funds the next rather than a programme that competes with every other demand on the operation. We sequence every initiative in ROI order, biggest recoverable cost first, and the opening build is usually an Operations Sprint that automates a single high-value step, most often intake and document extraction, and puts a working result into production in weeks. The same logic runs through our claims automation work and through the underwriting version of it, document automation for underwriting, where the highest-value first step is almost always the intake of the file rather than the judgment at the end. Healthcare operations follow the same shape, with the heaviest manual load usually sitting in eligibility, coding, and attachment handling ahead of the decision, which is the pattern we work through in healthcare claims automation.
What this looks like in a mid-market claims operation
Picture a third-party administrator handling a growing book across several carrier clients, each with its own portal and its own file format. The examiners are capable and the adjudication decisions are sound, but the operation has been meeting rising volume by hiring, and the quarterly pack reads as a healthy, scaling business. What the pack does not show is that a large share of examiner time goes to re-keying first notice of loss from one system into another, pulling reports from client portals, and keeping a compliance tracker current by hand so the audit trail survives an examiner moving on.
A vendor arrives offering straight-through adjudication, and on the clean, high-volume claims it performs well in the room. Rolled against the real book it stalls, because most files carry an exception the engine was never going to resolve, and the few denials it does produce raise exactly the accountability question the new state laws are built around. The automation that would have paid here was the hours of preparation the decision waits behind, not the decision itself, and no demo led with it because it is unglamorous and specific to how this one operation runs. That is the work a measurement surfaces and a vendor slide skips.
The questions worth asking the next vendor
The next time a vendor offers to automate your claims adjudication, the useful questions are about the work around the decision rather than the speed of it, because speed on the decision was never where the cost or the regulatory risk lived. Ask which specific steps the system takes off your examiners before they judge, how it handles the exceptions that make up most of a mid-market book, and who stays accountable for a denial when a regulator or a policyholder asks. An operation that can answer those three knows whether it is buying capacity it gets to keep or a decision it will later have to defend.